
How to read a trading Monte Carlo simulation
An attractive equity curve is easy to overinterpret. A simulation is more useful when you can explain what created every path, why the highlighted cases differ, and what the model leaves out.
RiskKit draws many possible win/loss sequences from one assumed win rate and reward:risk ratio. It applies your sizing rule after each trade, then compares final balances, drawdowns, target hits and a user-defined ruin floor. These are conditional scenarios, not forecasts.
Begin with expectancy, not the chart
Express a losing trade as −1R and an average winning trade as +bR. With win probability p, the simplified expected result per trade is p × b − (1 − p) R, before costs.
At a 45% win rate and an average win of 1.8R, expectancy is 0.45 × 1.8 − 0.55 = +0.26R per trade. The break-even win rate before costs is 1 ÷ (1 + 1.8) ≈ 35.7%.
Positive expectancy is only a property of these assumed averages. It does not mean each set of 100 trades is profitable. If win rate or average payoff changes, the simulation's premise changes too. Calculate expectancy from your own inputs before exploring the equity paths.
What each equity path represents
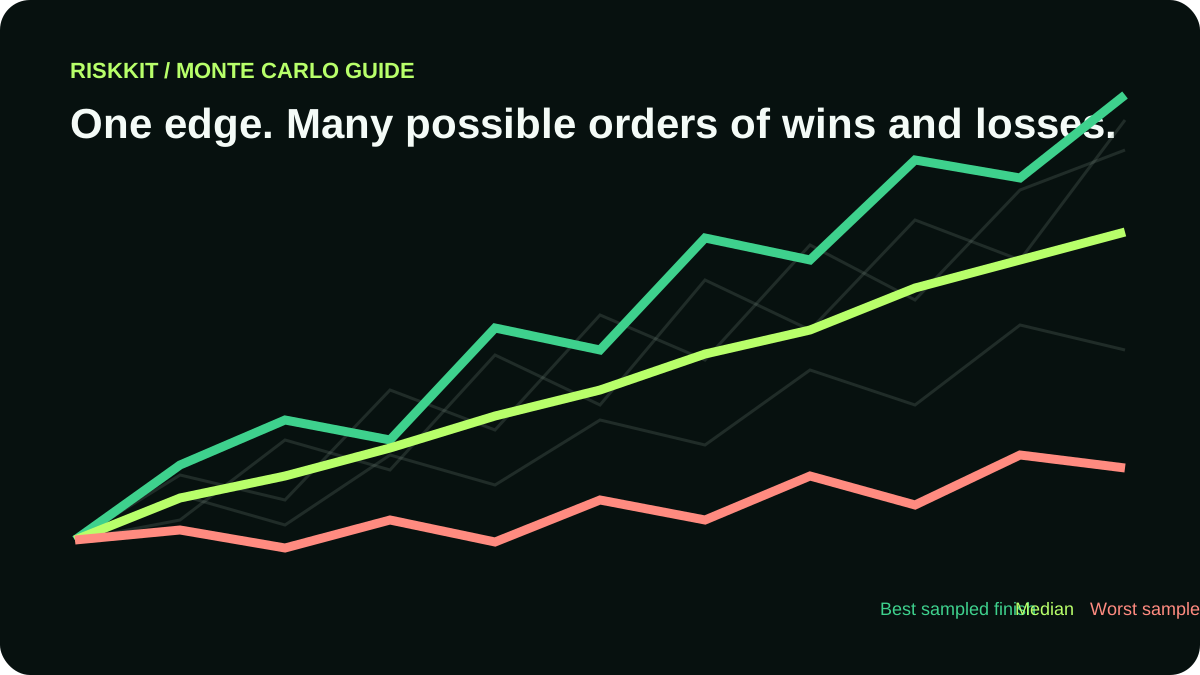
For every bot path, the simulator independently samples a win or loss on each trade using the entered win rate. A win adds the current cash risk multiplied by reward:risk; a loss subtracts the current cash risk. Risk is then recalculated according to the chosen fixed-risk or Kelly rule. The chart plots each bot's balance at the end of every simulated month.
The gray lines are all generated paths, not a confidence band. A fresh run samples new outcomes, so numbers can move even when inputs stay the same. More bot paths make the displayed fraction of paths less sensitive to one particular sample, but they do not repair inaccurate assumptions. For the probability of a particular loss run under this independent-trades assumption, use the Losing Streak Calculator.
The chart boundaries and the outcome cards answer different questions
At each simulated month, the chart's Best line is the highest balance among all generated bots, Median is the middle balance, and Worst is the lowest. These monthly boundaries can switch from one bot to another; they are not three continuous individual bot histories. No gray bot line should sit above the monthly maximum or below the monthly minimum at the same month.
The three outcome cards instead summarize actual bots ranked by final balance: highest finish, middle finish and lowest finish. Their drawdown, loss streak and target dates belong to those individual bots. The median card's final balance may match the chart's final-month median, but its earlier path need not follow the monthly median line. Even the worst sampled finish is not the worst outcome that could ever occur in live trading.
Questions to ask before increasing position size
Can a trading simulation tell me how to become wealthy?
No. It can test whether an assumed, repeatable edge and a chosen sizing rule produce acceptable survival and growth inside the model. It cannot establish that the edge exists or will persist after costs. Compare the Fixed Risk Simulator with the fractional Kelly Simulator, then stress-test a lower win rate and smaller average payoff. A faster best case is not evidence that a larger bet is sensible.
How much might my account retain after consecutive losses?
For a fixed percentage f of current equity lost per trade, the balance after k full losses is starting balance × (1 − f)k, assuming exact fills and no additional costs. For example, $10,000 with six consecutive 2% losses leaves $10,000 × 0.986 = $8,858.42. Use the Losing Streak Calculator to test your own balance and the probability of a run under its independent-trades assumption; a real gap can lose more than planned.
How many months or years could it take to double an account?
There is no reliable date without a real, durable edge. In either simulator, enter starting capital, win rate, realised reward:risk, the relevant risk setting, trades per month and a 2× target. The result reports the first simulated month each highlighted finishing bot reaches that level, if it does. Compare that with the share of all bots that reach the goal and the share crossing your ruin floor. Repeat with worse assumptions; the dates are conditional scenarios, not a timetable for future income.
Read the ruin floor literally
“Portfolio ruined below” is a threshold you choose as a percentage of starting capital. If a $10,000 account has a 20% floor, RiskKit counts a path as ruined when its balance reaches $2,000 or less. That does not mean the legal account balance is zero; it means the path crossed your chosen stop-trading line.
“Risk of ruin” is the share of simulated paths that cross that line within the selected horizon. “Failure / horizon” reports the first simulated month in which a highlighted path crosses it, or the end of the horizon if it survives. The month number is relative to the start of the run, not a calendar prediction.
Choose a sizing rule that matches your plan
Fixed risk
Use a percentage of current equity for continuous resizing, or fixed cash per cycle. In turnover mode, cash risk remains tied to the current cycle base until the portfolio passes the turnover target, when the base steps up. This model helps compare compounding against a staged-risk plan.
Open fixed-risk simulator →Fractional Kelly
Full Kelly is calculated from assumed win rate and average payoff; RiskKit then applies the selected fraction and a maximum-risk cap. For the 45% and 1.8R example, full Kelly is about 14.4% of equity. Quarter Kelly is about 3.6%, but a 2% cap limits the simulator to 2% per trade.
Open Kelly simulator →What this simulation cannot tell you
- Trades are sampled independently from a constant win rate and constant payoff. Market regimes, correlated losses and changing strategy performance are not represented.
- Spreads, commissions, slippage, financing, taxes and missed fills are not deducted. Use net results from your own records when estimating inputs.
- A stop loss may fill at a worse price than planned. Leverage or contract-specific margin events may end a real strategy before the model's balance floor.
- These paths describe a simplified model, not the probability distribution of future markets. Stress-test weaker win rates, smaller payoffs and larger risk before relying on any result.
Position sizing is only one part of a risk plan. CME Group's risk-management example illustrates why a percentage risk rule and the distance to a stop must be considered together. The original Kelly paper develops the growth-rate idea; it does not make an estimated trading edge certain.